 English
 Español
- Global Mobility
- Taxes
2027 US Custodian Matrix for Cross-Border RIAs: Fidelity, Schwab, Vanguard, Pershing & IBKR Rules by Client Country
When a US client relocates to London, Madrid, Paris, or Toronto, domestic custody assumptions break overnight. Use this custodian-by-custodian matrix to plan ACATS transitions before a 60-day freeze letter arrives.

Table of contents
Every cross-border RIA eventually gets the Friday afternoon forward: a US-citizen client who moved to London or Madrid six months ago updated their mailing address, and their retail US custodian just placed their taxable brokerage account into liquidation-only status.
Why domestic RIA custody breaks once a client crosses a border
Custodian restrictions come from three overlapping compliance layers: local broker-dealer registration rules in the client’s new country of residence, fund-issuer prospectus limits on US mutual funds outside the United States, and UK/EU PRIIPs retail disclosure rules that block Kid-less US-domiciled ETFs unless the firm exercises discretionary institutional authority or qualifies the client as an Elective Professional.
Custodian-by-custodian breakdown for 2027
- Fidelity (Retail & Institutional): Retail accounts with non-US residential addresses are generally restricted to closing trades, dividend cash-out, and cash withdrawals; new US mutual fund and options orders are blocked. Institutional RIA arrangements require country-by-country compliance review.
- Charles Schwab (Schwab International / Advisor Services): Supports a broad list of countries via Schwab One International, though country minimums, local solicitation rules, US mutual fund blocks, and UK/EEA PRIIPs retail ETF restrictions still apply.
- Vanguard: Does not onboard non-US residents and routinely freezes or issues transfer-out deadlines when existing retail households establish foreign residency.
- BNY Pershing / Clearing Custodians: Frequently used by cross-border RIAs with international clearing addenda for UK, EEA, Swiss, and APAC households, subject to advisory registration in both jurisdictions.
- Interactive Brokers (IBKR Advisor): Broad multi-currency and multi-entity footprint (US, UK, Ireland, Canada, Singapore, Hong Kong) with native FX execution, though entity migration changes SIPC/FSCS protection and local reporting feeds.
Pre-move 5-point transition checklist for advice firms
- Inventory every held-away retail account, 401(k), rollover IRA, Roth IRA, and 529 plan 90 days before the client’s tax residency date changes.
- Eliminate US mutual funds and non-HMRC-reporting ETFs (for UK movers) while the client is still solely US-resident, avoiding forced liquidations after local capital-gains or Spanish/French worldwide tax rules attach.
- Verify treaty treatment of Roth IRAs and employer pensions in the destination country (for example, filing a protective Canadian CRA Roth IRA election before any post-arrival contributions occur).
- Move taxable sleeves via in-kind ACATS rather than cash liquidation to preserve cost-basis lots and holding periods.
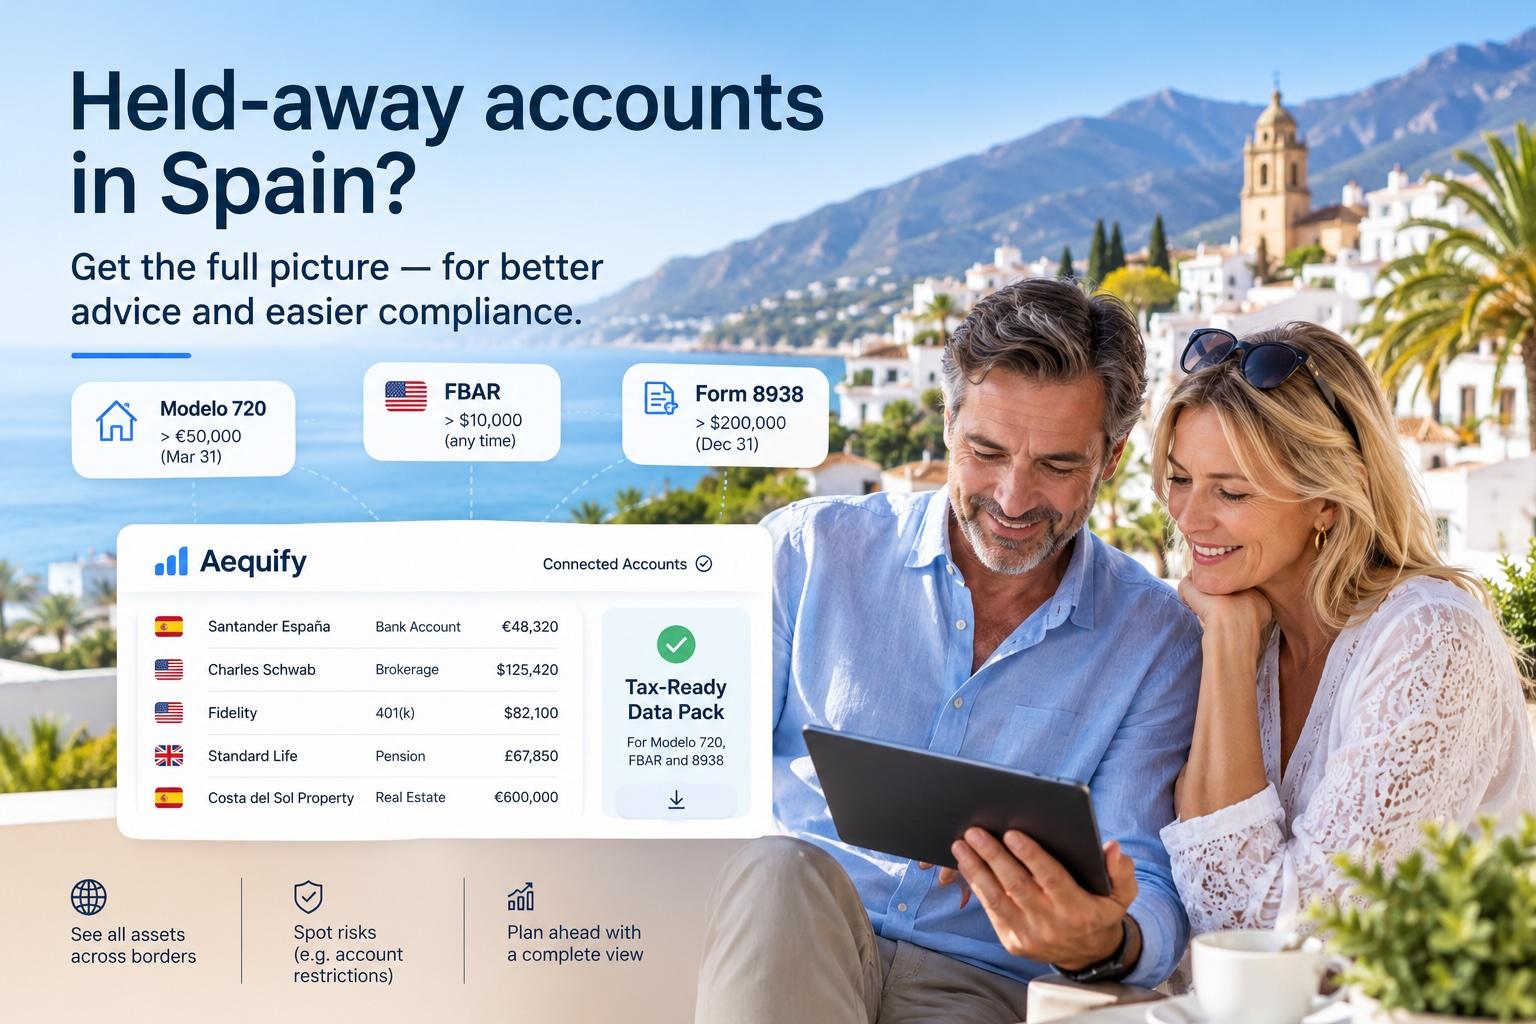
- Connect held-away foreign checking, ISA, and pension accounts in Aequify so the firm sees total household exposure, FBAR/Form 8938 thresholds, and PFIC traps continuously.
This article is for general informational purposes only and is not tax or legal advice. Rules can change, so confirm the current rules with a qualified tax professional before filing.
Advising US-connected clients abroad?
See held-away accounts, restricted US brokers and PFIC flags in one household view.
See sample household reportPay-as-you-go firm access
 SOC 2 Type II · View-only access · GDPR
 20-minute demo