 English
 Español
- Global Mobility
- Taxes
Advising Americans Moving Under the UK FIG Regime or Spain Beckham Law: 2027 Pre-Move Fact-Find Template
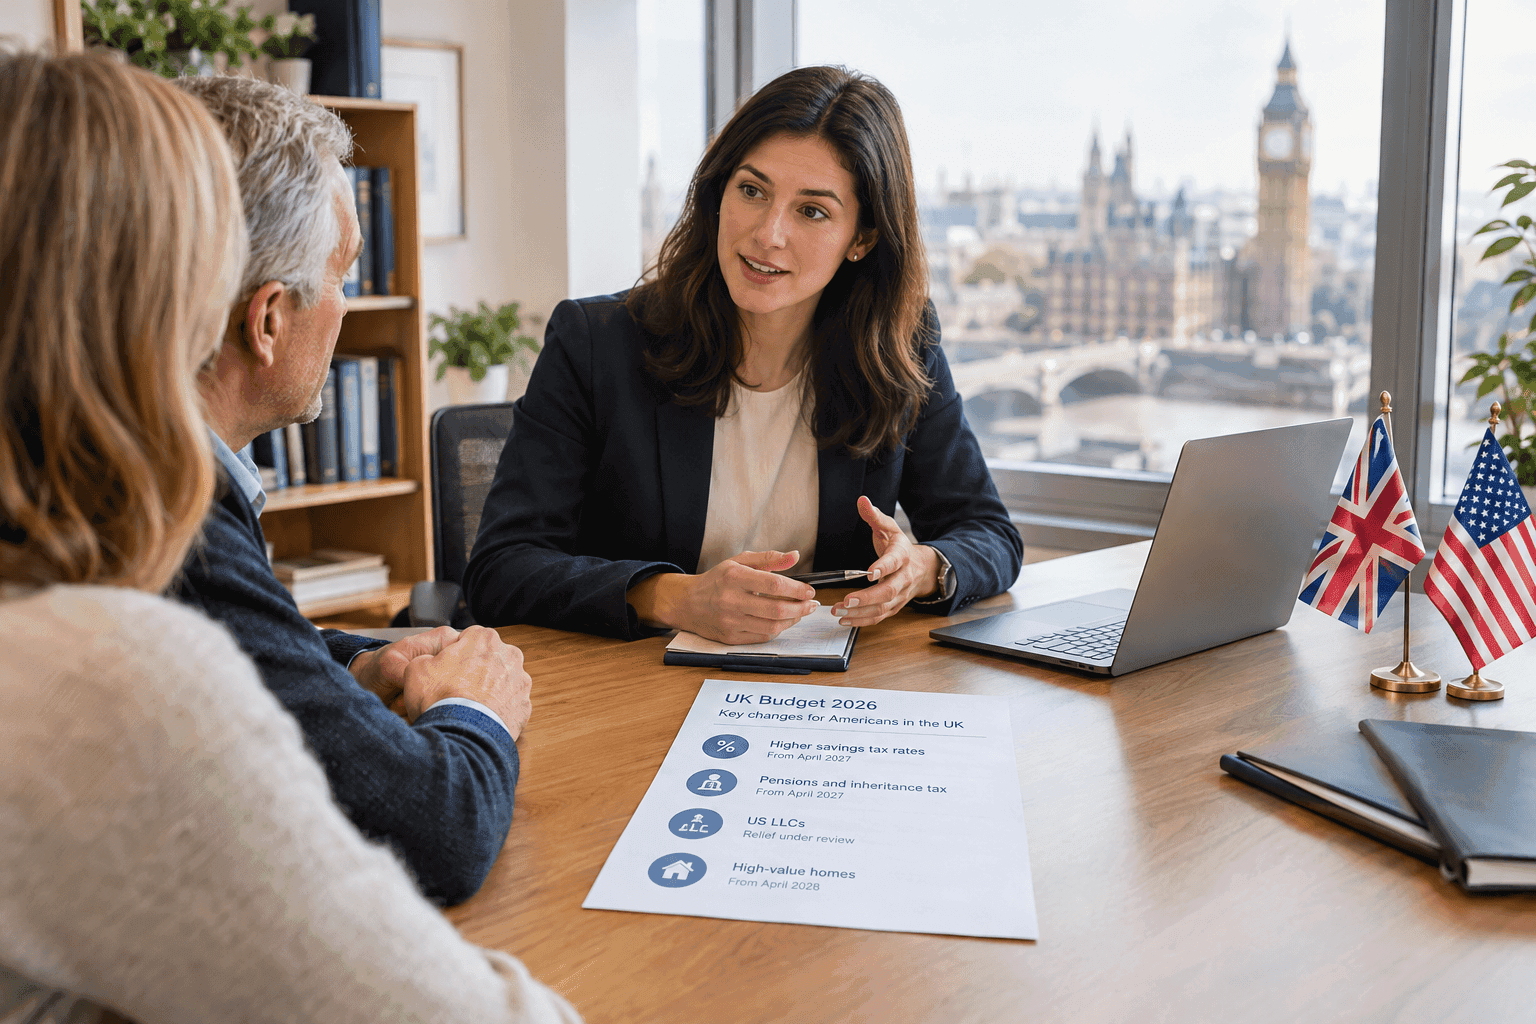
Both the UK’s 4-year FIG regime and Spain’s Beckham Law offer powerful windows for relocating Americans, yet US citizenship-based taxation turns standard non-dom playbooks upside down if accounts and equity grants aren’t sequenced before arrival.

Table of contents
For non-US expats, the UK’s 4-year Foreign Income and Gains (FIG) regime and Spain’s Régimen Especial de Trabajadores Desplazados (Beckham Law) look straightforward: shield eligible foreign investment income and gains during the window. For US citizens and green card holders, however, the IRS still taxes worldwide income, meaning a poorly timed asset sale or election loss of Foreign Tax Credits can leave the household worse off unless both sides of the return are modeled together.
UK 4-Year FIG Regime: What changes when the client holds a US passport
- 10-year non-UK residency test: Confirm the client has been non-UK tax resident under the Statutory Residence Test for at least 10 consecutive UK tax years prior to arrival.
- Loss of Personal Allowance & CGT annual exempt amount: Claiming FIG relief forfeits the UK Personal Allowance and Capital Gains annual exemption, so model whether UK salary levels make claiming FIG net-positive year by year.
- US still taxes the ‘exempt’ FIG gains: Realizing $500k of US tech stock under UK FIG shields UK CGT (24%), leaving only US federal + NIIT rates (up to 23.8%), an immediate multi-point tax arbitrage before year 5 brings full UK arising-basis taxation.
- HMRC Reporting Fund restructuring window: Years 1–4 give advisors a clean runway to exit non-reporting funds before Offshore Income Gains exposure kicks in at year 5.
Spain Beckham Law: US Social Security certificates, RSUs & Modelo 720 reliefs
- 6-month election deadline (Modelo 149): Missing the six-month window from Spanish Social Security registration (or US Certificate of Coverage start date) permanently disqualifies the client from the flat 24% employment rate up to €600,000.
- US-Spain Totalization Certificate of Coverage: Securing a US SSA Certificate of Coverage keeps an eligible seconded executive on US payroll taxes while preserving Beckham Law eligibility when structured properly.
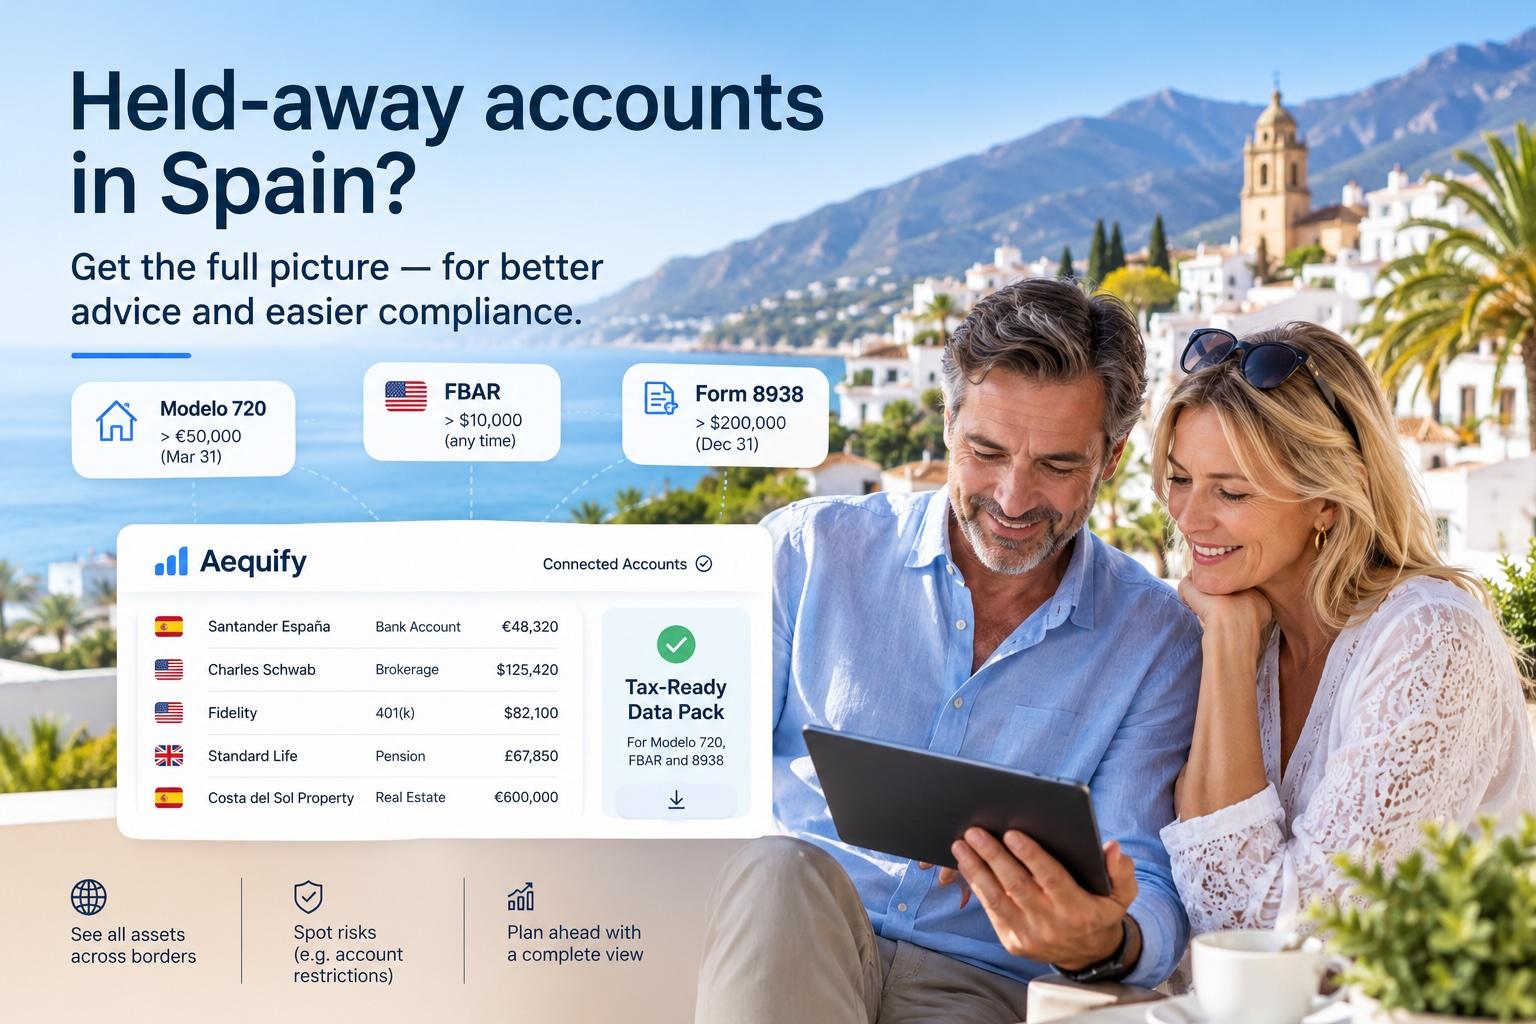
- Foreign brokerage & Modelo 720 relief: Beckham Law taxpayers are exempt from Modelo 720 informational filings (though spouses without their own Beckham election who co-own accounts are not!), while US FBAR and Form 8938 remain mandatory every year.
- Imputed Spanish primary-home income & RSU multi-country sourcing: Model RSU vest tranches earned across US and Spanish workdays carefully so Foreign Tax Credit baskets align.
This article is for general informational purposes only and is not tax or legal advice. Rules can change, so confirm the current rules with a qualified tax professional before filing.
Advising US-connected clients abroad?
See held-away accounts, restricted US brokers and PFIC flags in one household view.
See sample household reportPay-as-you-go firm access
 SOC 2 Type II · View-only access · GDPR
 20-minute demo