 English
 Español
- Taxes
FBAR vs Form 8938: Thresholds, Deadlines & Which You Must File (2026)
Learn FBAR filing requirements, how Form 8938 works, key deadlines, and the difference between FBAR and FATCA for U.S. expats abroad.

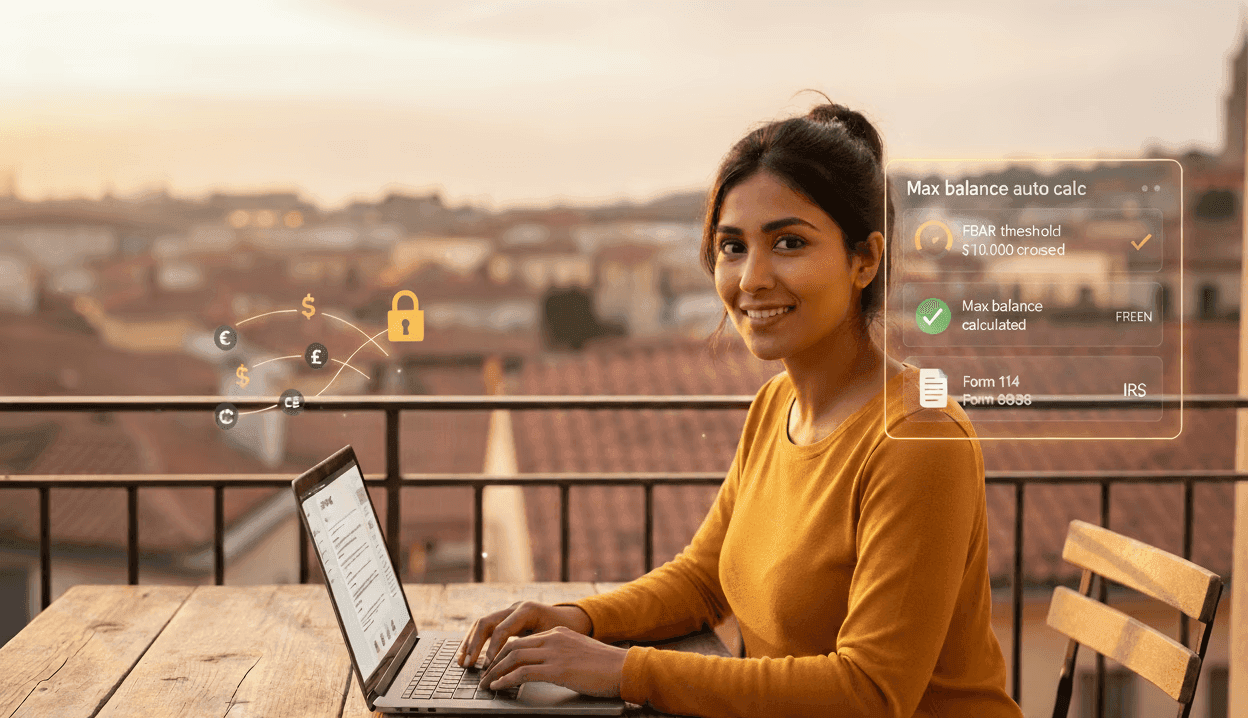
Table of contents
Life abroad as a U.S. citizen or Green Card holder can be incredibly fulfilling, but staying compliant with U.S. tax rules like FBAR and FATCA often feels like navigating a maze. The rules themselves are tricky enough, but the real challenge lies in gathering the right data, especially those elusive maximum account balances needed for FBAR filing.
The good news? This process just got a whole lot easier. While understanding FBAR and FATCA is still essential, Aequify, a platform built specifically for expats to manage their cross-border finances, has launched a new proactive Tax Insight feature that dramatically simplifies FBAR reporting, reducing what used to take hours down to just minutes.
This post breaks down the key differences between FBAR and FATCA, and shows how tools like Aequify are changing the game for U.S. expats.
What is FBAR?
The Foreign Bank Account Report (FBAR), officially FinCEN Form 114, is a U.S. anti-money laundering regulation that requires U.S. persons to report foreign financial accounts if their aggregate balance exceeds $10,000 USD at any point in the calendar year. This includes accounts you own or simply have signature authority over.
Unlike your tax return, FBAR is filed electronically with FinCEN, not the IRS. The challenge is that you need to track the highest balance of each foreign account during the year, an often tedious process requiring full of statement review.
This is where Aequify’s new feature becomes a game changer. Instead of manually reviewing every statement, you can now connect your foreign accounts to Aequify and let the platform do the work for you.
How Aequify Automates FBAR Compliance
Once you connect your non-U.S. financial accounts to Aequify’s secure platform and answer a few basic onboarding questions, the system automatically monitors balances and flags when your total crosses the $10,000 FBAR threshold.
Even better, Aequify calculates the highest balance reached for each connected account throughout the year, giving you exactly what you need to copy directly into FinCEN Form 114. No more guessing. No more spreadsheets. No more hours lost in paperwork.
Press enter or click to view image in full size
Aequify calculates the maximum balance for each connected account
What is FATCA?
The Foreign Account Tax Compliance Act (FATCA), on the other hand, is aimed at preventing offshore tax evasion. It requires U.S. taxpayers to report specified foreign financial assets if they exceed certain thresholds, which vary depending on your filing status and whether you live in the U.S. or abroad.
For U.S. expats, the thresholds are higher. For example, single filers living abroad must file Form 8938 if their foreign assets exceed $200,000 at year-end or $300,000 at any time during the year. FATCA includes more than just bank accounts — it can cover foreign mutual funds, foreign stocks held outside brokerage accounts, and even interests in foreign partnerships.
Form 8938 is filed with your annual U.S. tax return, and unlike FBAR, it’s governed by the IRS.
FBAR vs. FATCA: What’s the Difference?
Okay, here’s a simple text explanation of the key differences between FBAR and FATCA:
FBAR vs. FATCA: Key Differences Explained
FBAR (Report of Foreign Bank and Financial Accounts)
- Filed Using: FinCEN Form 114
- Agency: Handled by FinCEN (Financial Crimes Enforcement Network), part of the Treasury Department focused on financial crimes.
- Purpose: Primarily for anti-money laundering and law enforcement.
- How Filed: Must be filed electronically separately from your tax return through the BSA E-Filing System.
- Threshold: Required if the combined highest value of all your foreign financial accounts was more than $10,000 USD at any time during the year.
- What’s Reported: Focuses specifically on foreign financial accounts (like bank accounts, brokerage accounts).
FATCA (Foreign Account Tax Compliance Act)
- Filed Using: IRS Form 8938
- Agency: Handled by the IRS (Internal Revenue Service).
- Purpose: Primarily for tax compliance and preventing US taxpayers from hiding assets abroad to evade taxes.
- How Filed: Filed together with your annual US income tax return (Form 1040).
- Threshold: Required if the total value of your specified foreign financial assets exceeds much higher thresholds, which differ based on whether you live abroad and your tax filing status (starting at $200,000 for expats filing single, $400,000 for married filing jointly, on the last day of the year, or higher thresholds based on peak value during the year).
- What’s Reported: Covers a broader category of specified foreign financial assets. This includes accounts but can also include other things like foreign stocks or securities not held in an account, foreign partnership interests, etc.
Key Takeaway: FBAR and FATCA are separate requirements with different forms, different filing methods, different reporting thresholds, and slightly different focuses (accounts vs. broader assets). You might need to file one, the other, or both depending on your specific financial situation.
Filing Deadlines for 2024 (Filed in 2025)
- FBAR (Form 114): Due April 15, 2025, with an automatic extension to October 15, 2025.
- FATCA (Form 8938): Due with your income tax return — typically June 15, 2025, for expats, or October 15 if you file an extension.
Penalties for Missing the Mark
The stakes are high. Failing to file FBAR can result in penalties of up to $10,000 for non-willful violations, and up to $100,000 or 50% of account balances for willful violations. FATCA penalties start at $10,000 and can rise significantly for continued non-compliance.
How to Stay Compliant as a U.S. Expat
Start by identifying all your foreign financial accounts and assets. If you use Aequify, connect your foreign bank accounts to get automatic, accurate tracking of the highest balances for FBAR. For assets that aren’t supported or connected — such as foreign partnership interests or property — you’ll need to gather those manually and possibly consult a professional.
Once you’ve confirmed which thresholds you exceed, gather the necessary details: account numbers, institution names, asset values, and dates. Aequify makes this part easier by centralizing key FBAR data in one place.
Then, file your FBAR and Form 8938, if applicable, by the deadlines. Keep your records, and if anything seems unclear — especially when it comes to FATCA — it’s best to speak with a qualified expat tax advisor.
Final Thoughts
U.S. tax compliance doesn’t have to be stressful — even when you’re living abroad. With smart technology like Aequify’s proactive FBAR insight, you can spend less time buried in statements and more time enjoying life overseas.
You can access Aequify at www.aequify.com.
Disclaimer: This post is for informational purposes only and is not tax or legal advice. Tax laws change frequently and may vary based on your situation. Always consult with a qualified tax professional. Aequify’s FBAR feature is in beta. Verify the data to be sure of the accuracy.
 SOC 2 Type II · View-only access · GDPR
 15 days free
 Get the app